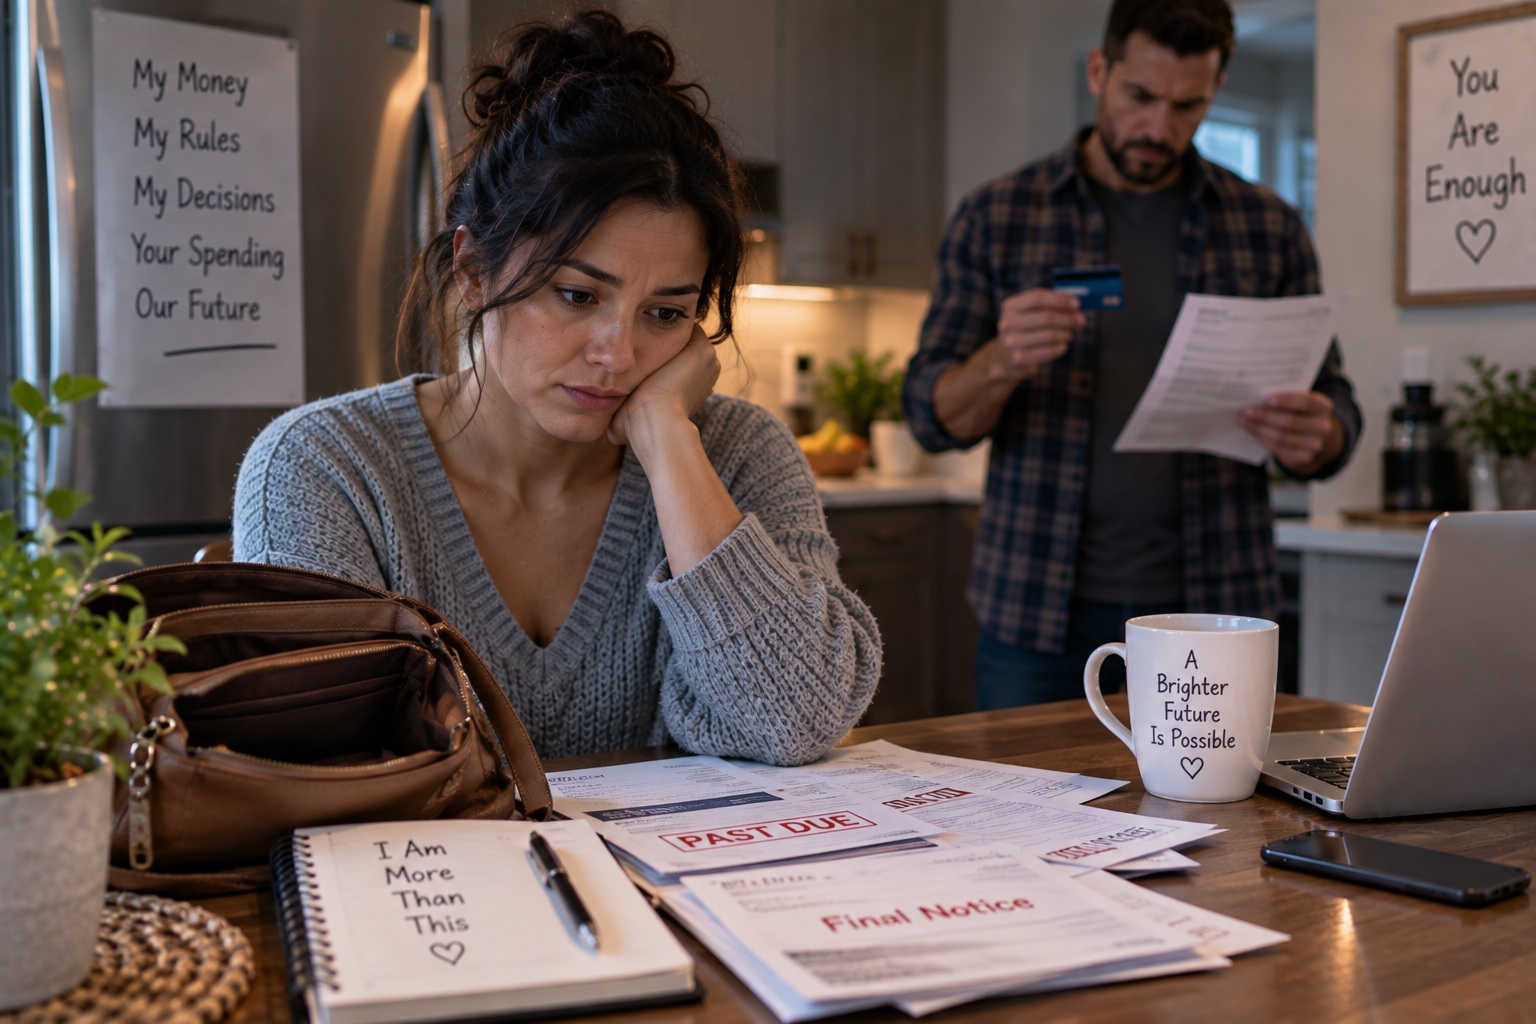
Financial Abuse: When Money Becomes a Means of Control
Financial Abuse: When Money Becomes a Means of Control
Imagine having a good job and earning your own paycheck—but having to ask permission to buy lunch.
Or discovering that credit cards have been opened in your name without your knowledge.
Maybe you don’t know the password to your family’s bank account.
Perhaps your partner questions every purchase you make, demands receipts when you come home, or gives you exactly enough money for groceries and expects you to account for every dollar.
Or maybe you’ve been discouraged from working altogether.
These situations can look very different, but they can have something important in common:
Money is being used to control another person.
This is known as financial or economic abuse, and it can be a powerful form of domestic abuse.
What Is Financial Abuse?
Financial abuse occurs when someone uses money, employment, credit, property, or access to financial resources to control another person or limit their independence.
Like other forms of coercive control, it isn’t always obvious at first.
Many couples naturally divide financial responsibilities.
One person might pay the bills while the other manages groceries. A couple might decide together that one parent will stay home with the children. Some couples combine every dollar they earn, while others maintain separate accounts.
None of those arrangements is inherently abusive.
The important questions are:
Do both people have a meaningful voice?
Can both people access the resources they reasonably need?
Can one person make ordinary decisions without fear of punishment?
Financial abuse isn’t really about who balances the checkbook.
It’s about power, restriction, and control.
It Can Start With “I’ll Take Care of Everything”
Financial control doesn’t necessarily begin with someone announcing:
“You aren’t allowed to have money.”
It may begin much more gently.
“You’re not good with finances. Let me handle everything.”
At first, that might even feel helpful.
Then passwords are changed.
Bank statements stop arriving.
Questions about money cause arguments.
Eventually, one partner has complete knowledge of the household finances while the other knows almost nothing.
How much is in savings?
What debts exist?
Whose name is on the house?
What retirement accounts are there?
Where are the tax returns?
The answer becomes:
“I don’t know. My partner handles all of that.”
The less someone knows about their financial situation, the harder it may become to imagine functioning independently.
Controlling Access to Money
One of the clearest forms of financial abuse is restricting someone’s access to money.
A controlling partner might provide an allowance, take the other person’s paycheck, restrict access to bank accounts, hide financial information, or refuse money for basic necessities.
They may require permission before any purchase.
Sometimes every transaction becomes an interrogation.
“What did you spend $12.47 on?”
“Why did you need that?”
“Where’s the receipt?”
The issue isn’t responsible budgeting.
Healthy couples absolutely discuss spending and financial priorities.
The difference is that one person shouldn’t have all the financial authority while the other is treated like a child who must ask permission.
You Can Earn Money and Still Be Financially Abused
This is an important misconception.
Financial abuse doesn’t only happen to someone who doesn’t work.
A person may earn $30,000, $80,000, or $150,000 a year and still have no meaningful control over their own money.
Their paycheck may be deposited into an account they cannot independently access.
Their partner may monitor every purchase.
They may be required to hand over bonuses, tax refunds, or other income.
The amount someone earns doesn’t necessarily tell us how financially independent they are.
Having income and having control over your financial life are not always the same thing.
Preventing Someone From Working
Employment creates more than income.
It can provide independence, health insurance, retirement savings, professional skills, social connections, and confidence.
That’s exactly why employment can become a target of financial abuse.
A controlling partner may pressure someone to quit.
They might repeatedly create emergencies that cause the person to miss work.
They may refuse to provide promised childcare or transportation.
They might constantly call or show up at the workplace.
They may deliberately start arguments before important meetings or interviews.
Eventually, the person may lose their job.
From the outside, it might look like an employment problem.
Behind closed doors, it may be part of a larger pattern designed to make independence more difficult.
Debt Can Be Used as a Weapon
Financial abuse isn’t limited to controlling the money someone already has.
It can also involve creating financial problems that follow a person for years.
An abusive partner may run up credit cards, misuse joint accounts, fail to pay bills, conceal debt, or use another person’s personal information improperly.
Someone may discover financial damage only when they try to rent an apartment, finance a car, or obtain credit on their own.
Suddenly, leaving isn’t just an emotional decision.
It’s a financial crisis.
Poor credit can affect housing.
Debt can consume income.
Missing financial records can make separating finances more difficult.
The relationship may end long before the financial consequences do.
Financial Abuse Can Look Different for Older Adults
Financial exploitation can also affect older adults.
A spouse, partner, relative, caregiver, or other trusted person may misuse bank accounts, pressure someone to change financial documents, take money without permission, or improperly use property or benefits.
Because older adults may depend on other people for transportation, healthcare, or daily assistance, recognizing and addressing financial exploitation can be especially complicated.
Changes in banking activity, unexplained missing money, unpaid bills despite adequate resources, or sudden changes in financial arrangements can deserve closer attention.
Children Can Become Part of Financial Control
When a couple has children, money can become an even more powerful means of pressure.
A controlling partner may withhold money for children’s necessities or threaten to stop providing financial support.
They may use childcare costs to prevent the other parent from working.
They may threaten:
“If you leave, you’ll have nothing.”
For a parent wondering how they will provide housing, food, transportation, childcare, and healthcare, that threat can feel very real.
Financial abuse can therefore affect an entire family, not only the person whose money is being controlled.
Why Financial Abuse Makes Leaving So Difficult
It’s easy for someone outside an abusive relationship to say:
“Why doesn’t she just leave?”
Now imagine leaving with $40 in your wallet.
No credit card.
No independent bank account.
No access to household savings.
No recent employment history.
Damaged credit.
Two children.
And nowhere to stay.
Suddenly, “just leave” doesn’t sound simple at all.
Financial abuse can create exactly this kind of dependence.
Even someone who recognizes that a relationship is abusive may genuinely have no idea how they could afford to leave.
That’s one reason financial control can be so effective.
It doesn’t merely make someone afraid to leave. It can systematically remove the resources they would need to do it.
The Emotional Impact Goes Beyond Money
Financial abuse isn’t only financially damaging.
Imagine being an adult who has to ask permission every time you need something.
Over time, it can change the way you see yourself.
Someone may begin feeling incapable of handling money.
They may become afraid to make decisions.
They may feel embarrassed that they don’t understand their own finances.
They may believe they could never support themselves.
And because money touches almost every part of adult life, financial control can become control over much more than spending.
It can affect where someone lives.
Whether they can work.
Whether they can see friends.
Whether they can obtain healthcare.
Whether they can travel.
Whether they can leave.
Controlling money can become a way of controlling someone’s choices.
The Impact Can Last for Years
Even after someone leaves an abusive relationship, the financial consequences may remain.
They may need to rebuild credit.
Find employment.
Replace financial documents.
Open new accounts.
Resolve debt.
Secure housing.
Learn financial skills they were never allowed to practice.
Reestablish savings.
Recover professionally after years outside the workforce.
That recovery doesn’t necessarily happen overnight.
For some survivors, rebuilding financial independence is one of the longest parts of rebuilding their lives.
What Does a Healthy Financial Relationship Look Like?
Healthy couples don’t necessarily split everything 50/50.
One person may earn significantly more.
One may stay home with children.
One may be much better at managing investments or paying bills.
That’s fine.
Equality doesn’t require identical roles. It requires mutual respect and meaningful participation.
Both partners should generally understand their financial situation.
Major financial decisions should involve both people.
Each person should be able to ask questions without fear.
No one should have to earn access to basic necessities through obedience.
And money shouldn’t be used to punish, threaten, humiliate, or trap someone.
If You’re Wondering Whether You’re Experiencing Financial Abuse
Ask yourself a few questions.
Do I have reasonable access to our financial information?
Do I know what accounts and debts we have?
Can I access money for ordinary necessities?
Am I afraid of my partner’s reaction when I spend money?
Does my partner prevent or interfere with my ability to work?
Has money or debt been placed in my name without my informed agreement?
Does my partner use money to threaten or punish me?
Could I access some financial resources in an emergency?
And perhaps most importantly:
Do I participate in our financial decisions—or am I simply expected to follow them?
No single answer tells the whole story.
But a repeated pattern of financial restriction combined with fear, intimidation, or control should not be ignored.
If Someone You Know Is Being Financially Controlled
Avoid asking why they haven’t left.
Instead, listen.
Don’t shame them for not knowing more about their finances. A controlling person may have deliberately kept them from learning.
You might say:
“I believe you.”
“You deserve to have a say in your own financial life.”
“What would help you feel safer?”
“Would you like help finding someone who understands financial abuse?”
And be careful about confronting the abusive partner or taking actions on someone’s behalf without discussing the potential consequences with them.
Safety should come first.
Rebuilding Financial Independence
For someone safely preparing for greater independence, small steps can eventually become meaningful ones.
That might involve learning more about household finances, understanding credit, gathering important financial information, speaking confidentially with a domestic-violence advocate, or getting professional financial or legal guidance.
But everyone’s circumstances are different.
If a controlling partner monitors devices, accounts, mail, or spending, even seemingly ordinary financial actions could potentially be noticed.
A personalized safety plan is more important than following a generic checklist.
Domestic-violence advocates can help someone think through those risks confidentially.
Financial Freedom Is Part of Personal Freedom
Money isn’t everything.
But in modern life, money affects nearly everything.
Housing.
Food.
Transportation.
Healthcare.
Employment.
Education.
Childcare.
And the ability to make choices about your own future.
That’s why financial abuse can be so devastating.
It doesn’t always look dramatic from the outside. There may be a nice house, two cars in the driveway, and plenty of money in the bank.
But none of those things tells you whether both people inside that home have freedom.
Financial abuse isn’t defined by how much money a family has. It’s about whether money is being used to control another person’s life.
And recognizing that difference can be an important first step toward rebuilding independence.
Help Is Available
If you or someone you know is experiencing financial abuse or another form of domestic violence, confidential support is available through the National Domestic Violence Hotline at 1-800-799-SAFE (7233) or by texting START to 88788.
If you believe your phone, computer, financial accounts, or internet activity may be monitored, consider using a safer device when seeking help.
If you are in immediate danger, contact emergency services.
You don’t have to have bruises to ask for help. And you don’t have to have an empty bank account for financial control to be abuse.